 Itô calculus
Common
Rarity: Common
The most frequent rarity: most Wikipedia articles become Commons.
Rarity follows how well known the article is: its views on the French and English Wikipedia over a year, and the number of languages it exists in.
At a glance
- Class
- Notion
- Domain
- Science and technology
- In collections
- Nobody has pulled it yet.
What Wikipedia says
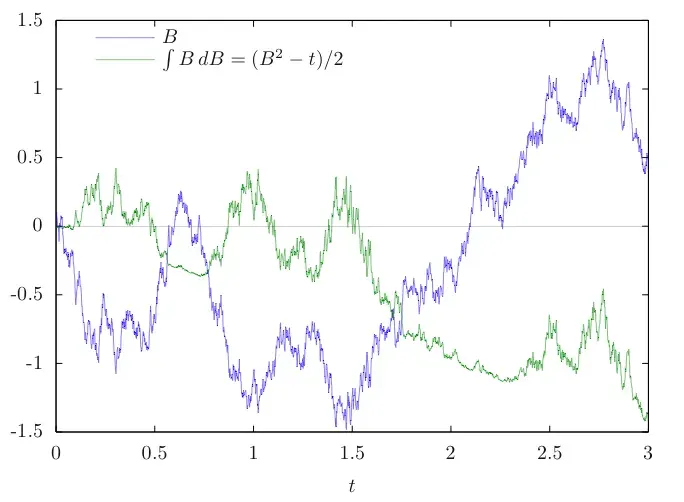
Itô calculus, named after Kiyosi Itô, extends the methods of calculus to stochastic processes such as Brownian motion (see Wiener process). It has important applications in mathematical finance, in stochastic differential equations, and more recently even in machine learning.
Excerpt from the Wikipedia article “Itô calculus”, under the CC BY-SA 4.0 license. Read the article on Wikipedia
Image: Roboquant, CC BY 3.0, via Wikimedia Commons.
Open free boosters and add Itô calculus to your collection.
Play for free